Most restoration owners lose high-value jobs before the phone rings. A homeowner compares three quotes, picks the lowest, and calls you back six months later when the mold returns. A well-built restoration not cheapest page stops that cycle by framing your price difference as risk reduction.
This post walks you step by step. You will learn how to write pricing-defense copy that reads as documentation and standards, not an upsell. The result attracts larger insurance claims and homeowners who want the work done right.
The trick is signaling credibility to adjusters and property owners at the same time. Do it wrong and you sound defensive. Do it right and you become the obvious choice.
Why a Restoration Not Cheapest Page Beats a Price List
A “we’re not the cheapest” page is a dedicated landing page that explains your pricing difference using standards, documentation, and claim-friendly methods. It never posts dollar figures.
Restoration pricing works differently from general home services. Carpet cleaners quote flat rates. You bill against Xactimate line items that an adjuster approves.
Posting prices hurts you two ways. First, it anchors homeowners to a number before they understand the scope. Second, it makes insurance work look like retail work.
Your goal is to justify your methods, not your math. Adjusters already know fair market pricing. Homeowners need to trust that you follow the right steps.
What Makes Restoration Buyers Nervous
Two readers land on this page. The cash-paying homeowner worried about overpaying. The claim-holding homeowner worried about a botched repair.
Both fear the same thing: paying twice. Your copy should name that fear directly and show how your standards prevent it.
Quality Messaging on Your Restoration Website Without Sounding Expensive
Quality messaging on a restoration website means proving your standards with evidence, not adjectives. Words like “best” and “trusted” signal nothing. Documented moisture logs and IICRC certifications signal everything.
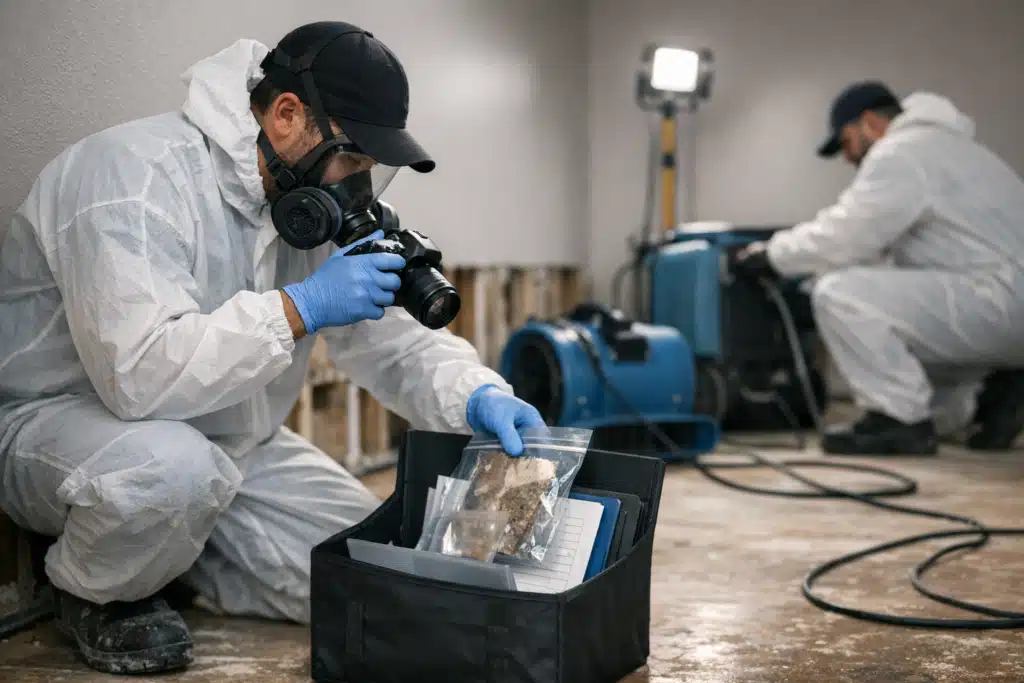
Replace vague claims with specific proof. Here is the difference in practice.
- Weak: “We provide superior water damage service.”
- Strong: “We document moisture readings every 24 hours until your drywall hits dry standard, so the insurer has proof and you avoid hidden mold.”
The strong version names a method, a frequency, and a payoff. It reads like a job spec, not a sales pitch.
Lead With the Risk, Not the Price
Open your page by naming what a cheap job costs later. A low bidder who skips containment can spread mold spores across two more rooms.
That turns a $4,000 claim into a $14,000 claim. Frame your standards as the thing that keeps the claim clean and the home safe.
The Five-Block Copy Framework for Your Page
Use this structure to build a page that satisfies both homeowners and adjusters. Each block does one job.
- The honest headline. State plainly that you are not the cheapest and that there is a reason. Honesty disarms skepticism faster than any guarantee.
- The hidden-cost section. Show what low bids leave out: proper containment, documented drying, and code-compliant rebuilds.
- The standards list. Name your certifications and methods. IICRC credentials, moisture mapping, and daily logs carry weight with insurers.
- The adjuster-friendly block. Explain that you bill to Xactimate, supply photo documentation, and work directly with the carrier.
- The reassurance close. Confirm you handle claims of every size and that estimates are free. No price, no pressure.
Block four matters most for insurance work. When a homeowner reads that you “document everything the adjuster needs,” they relax. They stop worrying about out-of-pocket surprises.
Example Language for the Adjuster Block
Write it from the homeowner’s point of view, not yours. Try this framing.
“We photograph every affected area before and after, log moisture daily, and submit line-item estimates in the format your insurer expects. That paperwork protects your claim and speeds your approval.”
This single paragraph does more to win insurance jobs than any discount ever could. It removes the fear of a denied or underpaid claim.
How to Avoid the Premium-Upsell Trap
Homeowners distrust pages that scream luxury. The moment your copy sounds like a car dealership add-on menu, trust drops.
Keep these rules in mind as you write.
- Name the method, skip the adjective. “HEPA air scrubbers run continuously” beats “advanced equipment.”
- Tie every standard to a homeowner benefit. Containment prevents cross-contamination, which prevents a second claim.
- Use plain numbers where you can. “We re-check moisture for three to five days” tells a real story.
- Mention insurance early. It signals you handle claims daily and reduces billing anxiety.
The difference between “standards” and “upsell” is proof. Standards cite a method. Upsells cite your opinion of yourself.
Back Claims With Visible Evidence
Add photos of real documentation. A screenshot of a moisture log or a redacted Xactimate estimate proves you do the work.
Most restoration sites show stock photos of flooded basements. Show your paperwork instead. Proof of process converts better than proof of damage.
Connect the Page to Your Lead Flow
A page alone wins nothing. Link to it from your water damage, fire, and mold service pages right before each call-to-action.
Place it in the spot where price objections form. A reader comparing quotes clicks it, reads your reasoning, and calls with confidence.
Track performance by source. Tag the page in your analytics and note how many callers reference it during the first conversation.
- Watch the close rate on leads who viewed the page versus those who did not.
- Note whether insurance jobs make up a larger share of page-viewer calls.
- Ask your intake staff to log which objections the page already answered.
If your average claim size climbs after launch, the page is doing its job.
Timing the Page for Storm Season
Publish and promote this page before your busy months, not during them. A homeowner shopping during a storm surge has less patience for comparison.
Feed traffic to it with seasonal ads. During hail or freeze season, point paid clicks to your service page, then let the price-objection link do the quiet convincing.
This matters because storm-driven leads skew toward insurance claims. Your adjuster-friendly block speaks directly to that crowd when demand spikes.
Conclusion
A strong restoration not cheapest page wins higher-value jobs by replacing price defense with documented standards and claim-ready proof. Lead with risk, show your paperwork, and speak to adjusters and homeowners in the same breath. Build it before storm season and track which leads it converts.
Want a page written to attract insurance claims without posting prices? Call or text The Restoration Marketers at 720‑885‑0749 or visit https://restorationmarketers.com.